
Chance of Success
A percentage is the share of simulated paths that last through the plan.
Read Chance of Success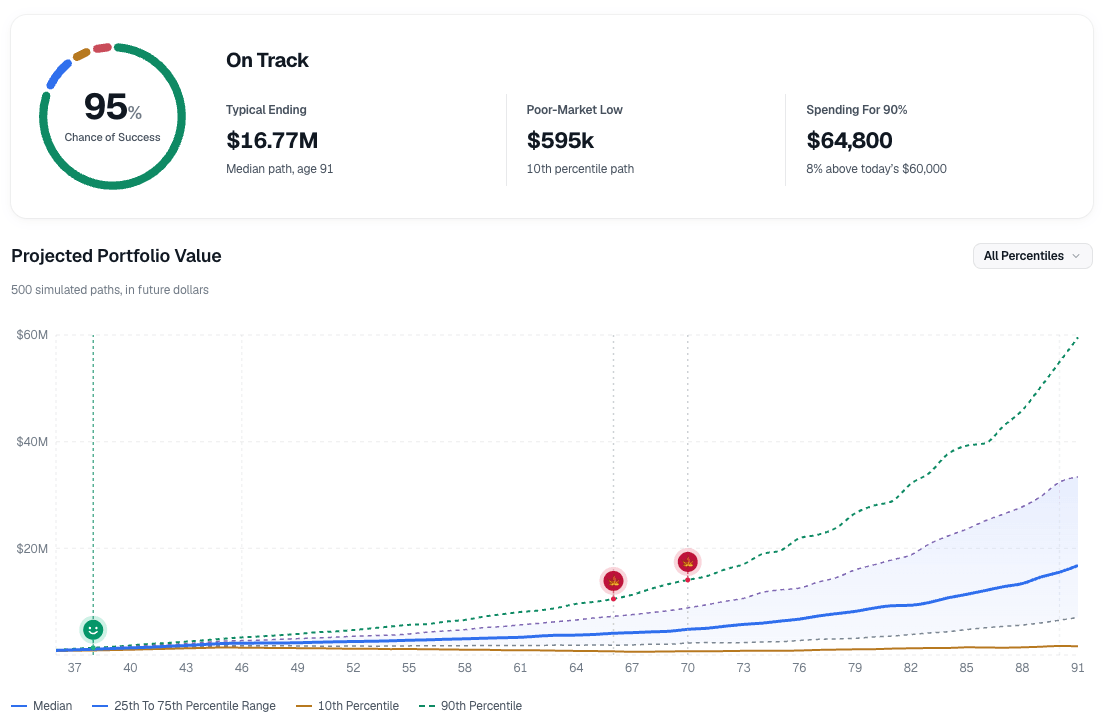

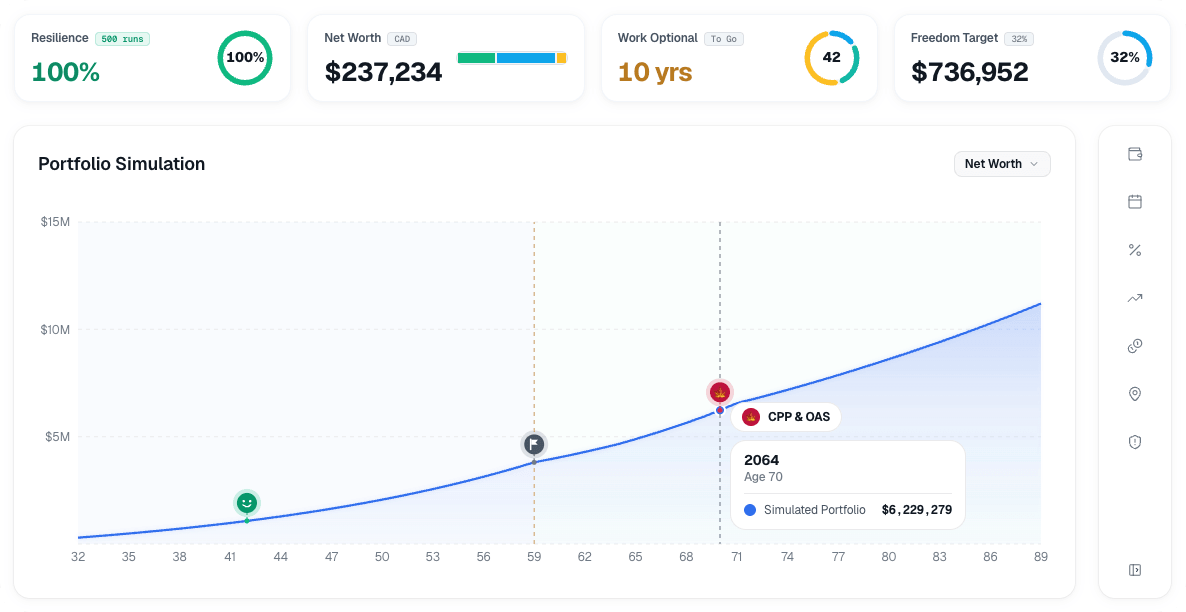
Free tools, each built around one question. Use them on their own, or let the planner connect them.
A percentage is the share of simulated paths that last through the plan.
Read Chance of Success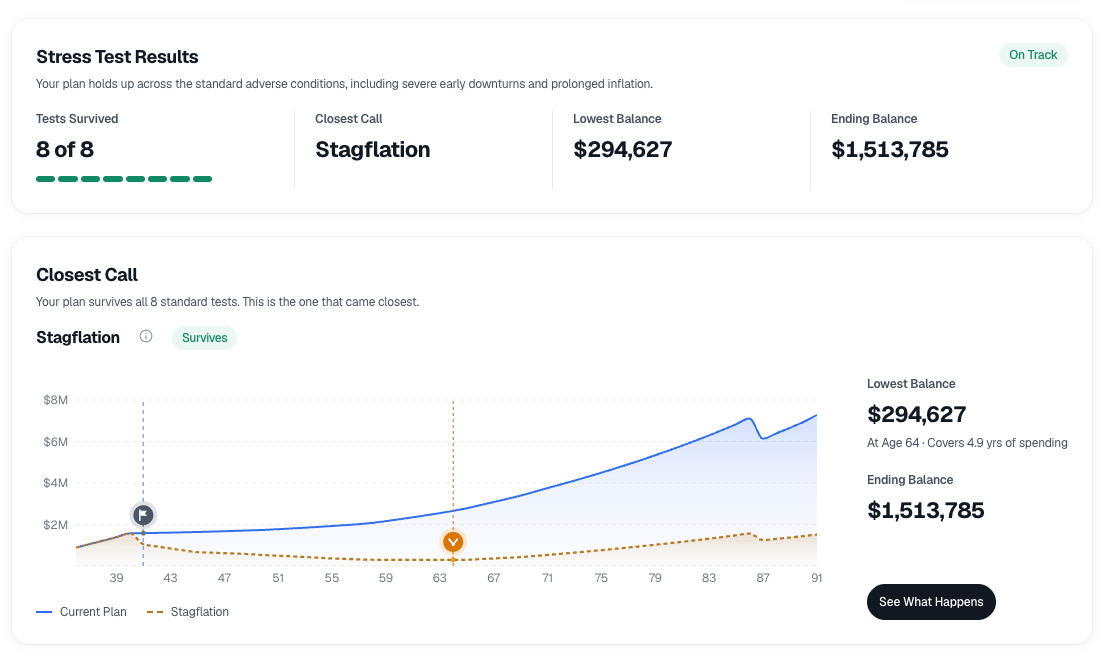
You can turn one change on, see the trade-off, and leave your plan untouched.
Read Optimizations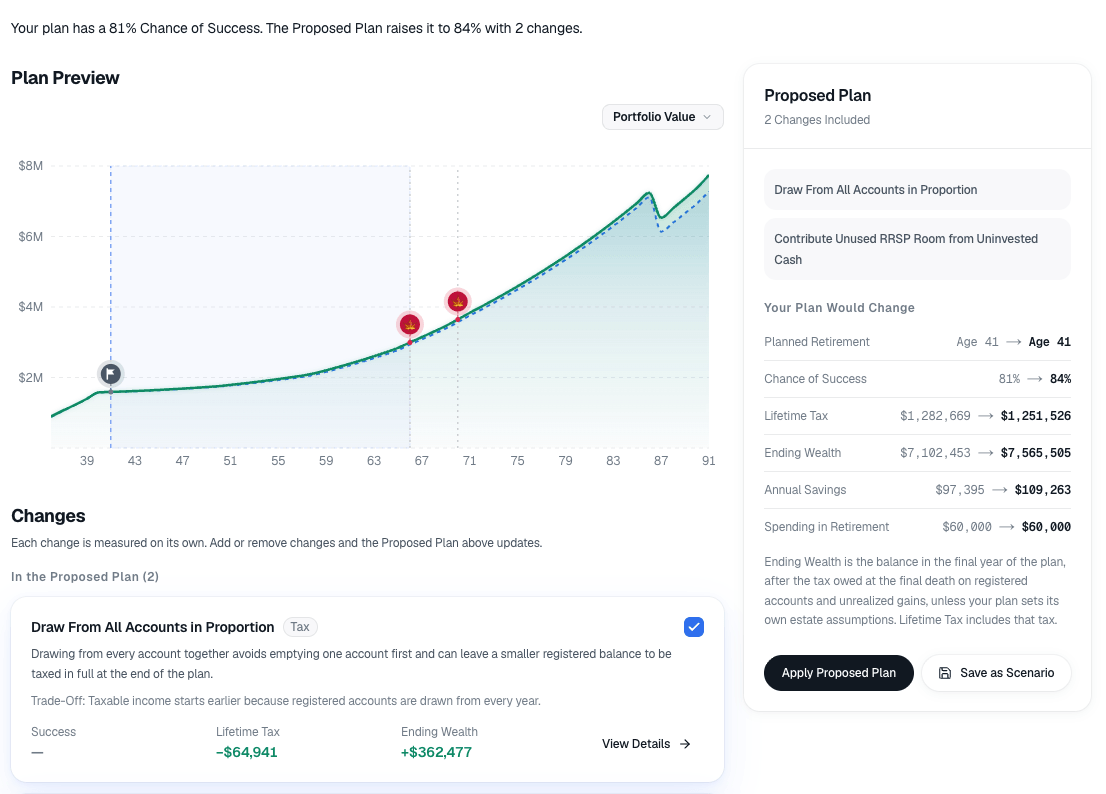
Starting CPP and OAS earlier or later changes the plan, not just the pension cheque.
Read Benefits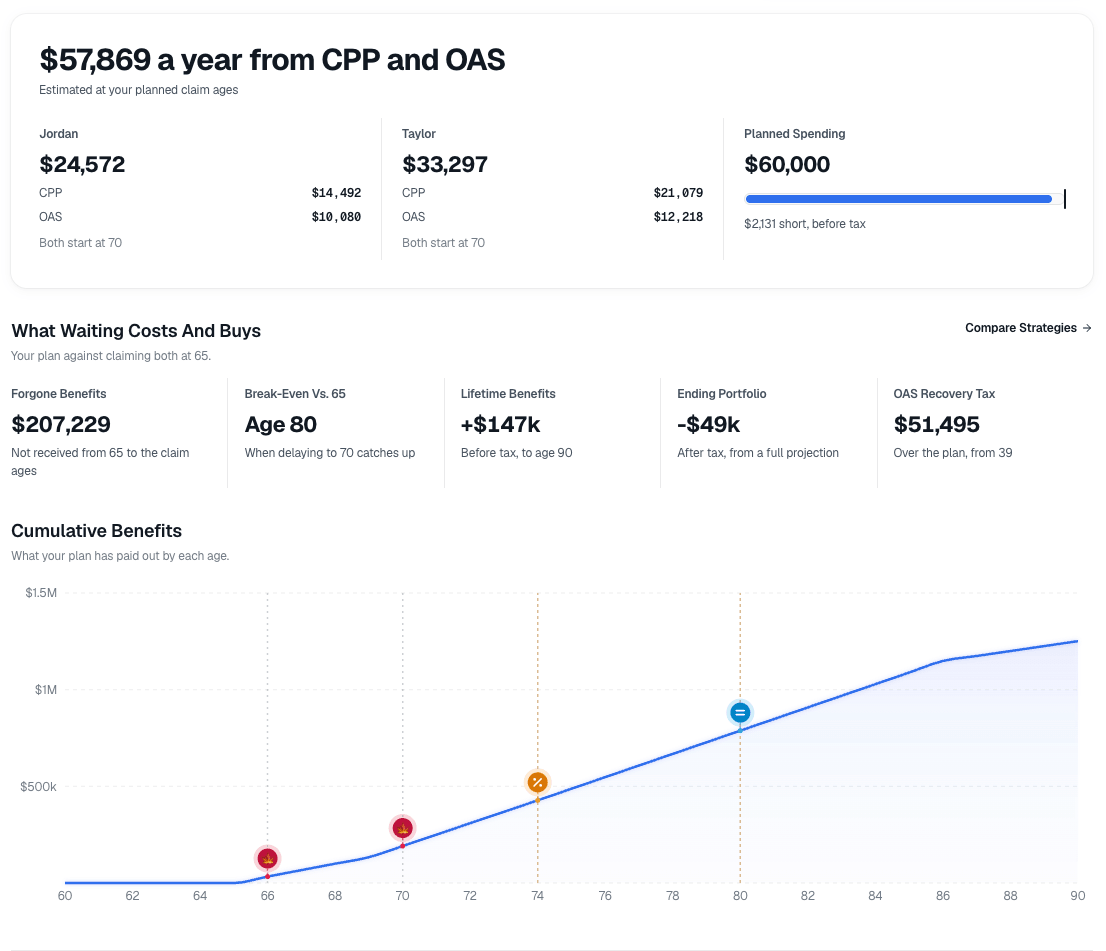
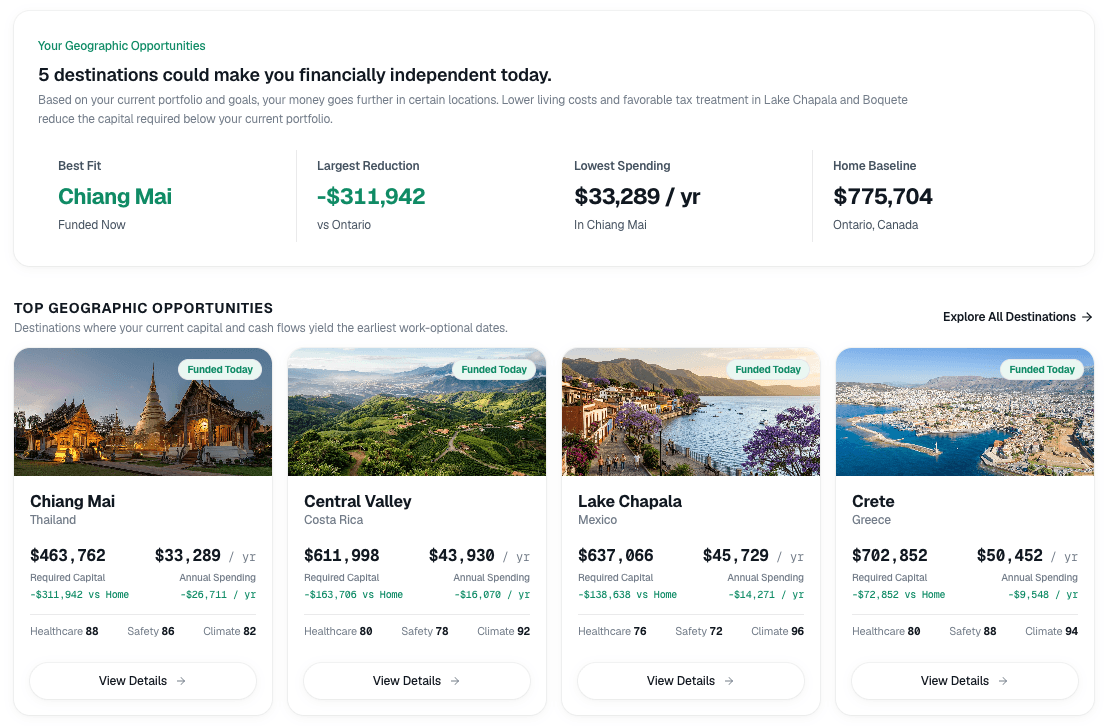
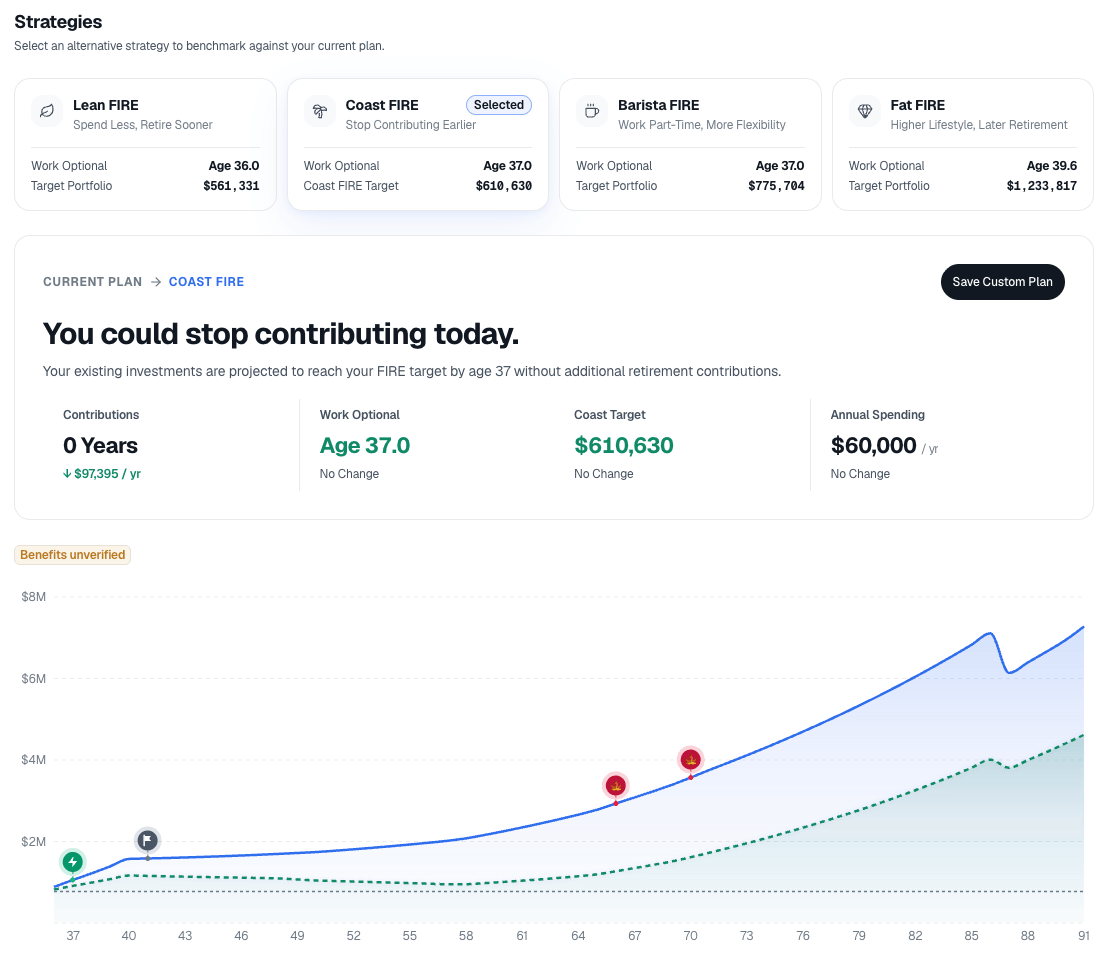
Taxes, benefits and account rules sit in the same plan, not in footnotes. American tools think in Roth IRAs and Social Security. nomorework started from the Canadian rulebook.
Each account has its own tax rules, so the plan tracks them separately.
Every dollar of income is taxed once and tested against the benefits it can reduce.
Retirement decisions rarely touch just one income.
Where the money comes from, and how much you spend each year, shapes how long it lasts.
Straightforward starting points for common Canadian retirement questions.
Transparent Pricing
Build your baseline retirement plan, model your timeline, and test core assumptions.
Complete Canadian retirement modeling with tax optimization and stress analysis.
Next: we email you a 6-digit code (no password), then you pay securely via Lemon Squeezy · Cancel anytime
Yes. nomorework never asks for your bank or brokerage logins, and there is nothing to link. Your plan is saved in your browser. We don't sell your information or run tracking ads.
Explorer is free. The Planner is $49.99 CAD a year, $4.99 CAD a month, or $199 CAD once. You can start with Explorer and upgrade later if you want more.
No. nomorework is an educational tool. It gives estimates based on 2026 tax rules and the numbers you enter, and it doesn't know your whole situation. Check big decisions with a planner or an accountant. See what is and is not modeled
Most bank calculators use one return and one spending number. nomorework runs your plan year by year through federal and provincial tax, CPP and OAS timing, RRIF minimums and the OAS recovery tax, then tests it against market crashes. The calculators on this site answer one question at a time, and the planner connects them.
Yes. It covers all ten provinces and three territories, including Quebec's tax brackets, credits and QPP.
That is the risk the stress tests are for. They apply defined 2008-style and other market shocks to your plan and show the modeled balance path and recovery, before you stop working. These are parameterized scenarios, not literal historical replays.
You can back up and restore all of your entered plan data for free. The full year-by-year ledger and CSV export require Planner. You can cancel a subscription from your account settings, and you keep access until the end of the period you paid for.
A few minutes. The quick start asks for your age, savings, income and spending. After that you can go deeper into tax, benefits and relocation whenever you like.
Hi, I'm an independent builder here in Canada. nomorework isn't run by a bank or an insurer, and there's no advisor to talk to or managed product to buy. The tool is the whole business. Read more on the About page